AI vs. automation in fintech: How to tell them apart

- What's the difference between AI and automation?
- AI vs. automation across financial services and finance
- Three signs a finance tool uses genuine AI
- Three tests to run on a vendor demo
- How Ramp's AI agents close the loop for finance teams
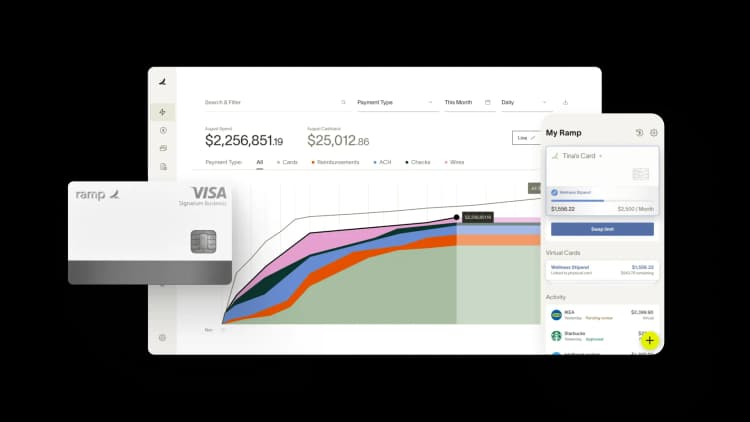
Automation follows fixed, pre-written rules, while AI reasons through situations those rules never anticipated. That line matters because many finance tools now marketed as AI are rules-based automation wearing a new label. The cost of that confusion lands on you when a transaction the rules never covered slips through or stalls.
You don't have to take the label on faith because three concrete checks in a demo separate genuine AI from automation wearing a new name.
What's the difference between AI and automation?
Automation executes a set of predetermined steps every time, and AI evaluates the inputs in front of it and decides what to do, including in cases no rule was ever written for. The simplest automation definition is a system that runs an "if this, then that" instruction without judgment. AI starts where that logic runs out: It weighs context, makes a call, and can handle an input it's never seen before.
Finance teams evaluating spend, close, accounts payable, and procurement tools are the ones who pay for the gap when a tool sold as intelligent turns out to break on anything outside its script.
| Dimension | Rules-based automation | AI |
|---|---|---|
| How decisions are made | Follows pre-written rules and thresholds set in advance | Evaluates the specific inputs and decides, weighing context |
| Behavior on an unfamiliar case | Fails, skips, or routes to a human because no rule matches | Reasons through it and makes a call it can justify |
| Whether it improves over time | Static until someone rewrites the rules | Learns from corrections and adjusts future decisions |
| What a human does | Writes and maintains every rule, handles all exceptions | Confirms decisions and steps in on genuine judgment calls |
| Typical finance examples | Receipt-matching thresholds, recurring journal entries | Coding an unfamiliar invoice, flagging an odd transaction |
Get the label wrong and you buy a tool that needs you to anticipate every edge case in advance, which defeats the reason you were shopping for help.
AI vs. automation across financial services and finance
The same split shows up in day-to-day finance work, not just in fintech product pages. Across financial services, a rules-based system does exactly what its script says and stops the moment reality steps outside that script, while genuine AI keeps going. This plays out in three situations your finance team encounters every month:
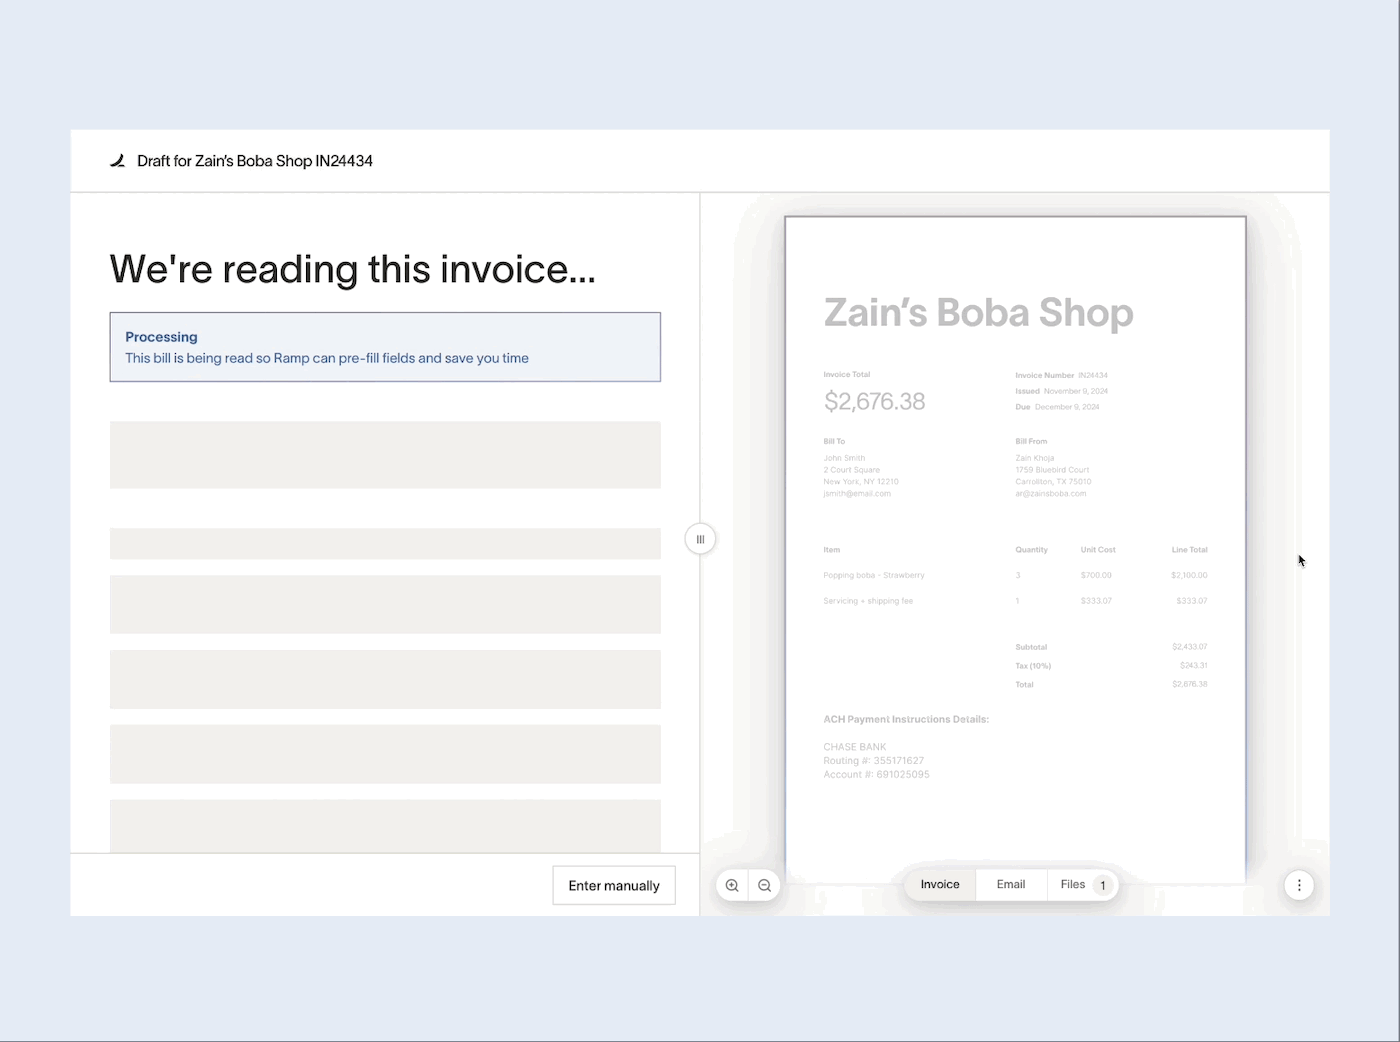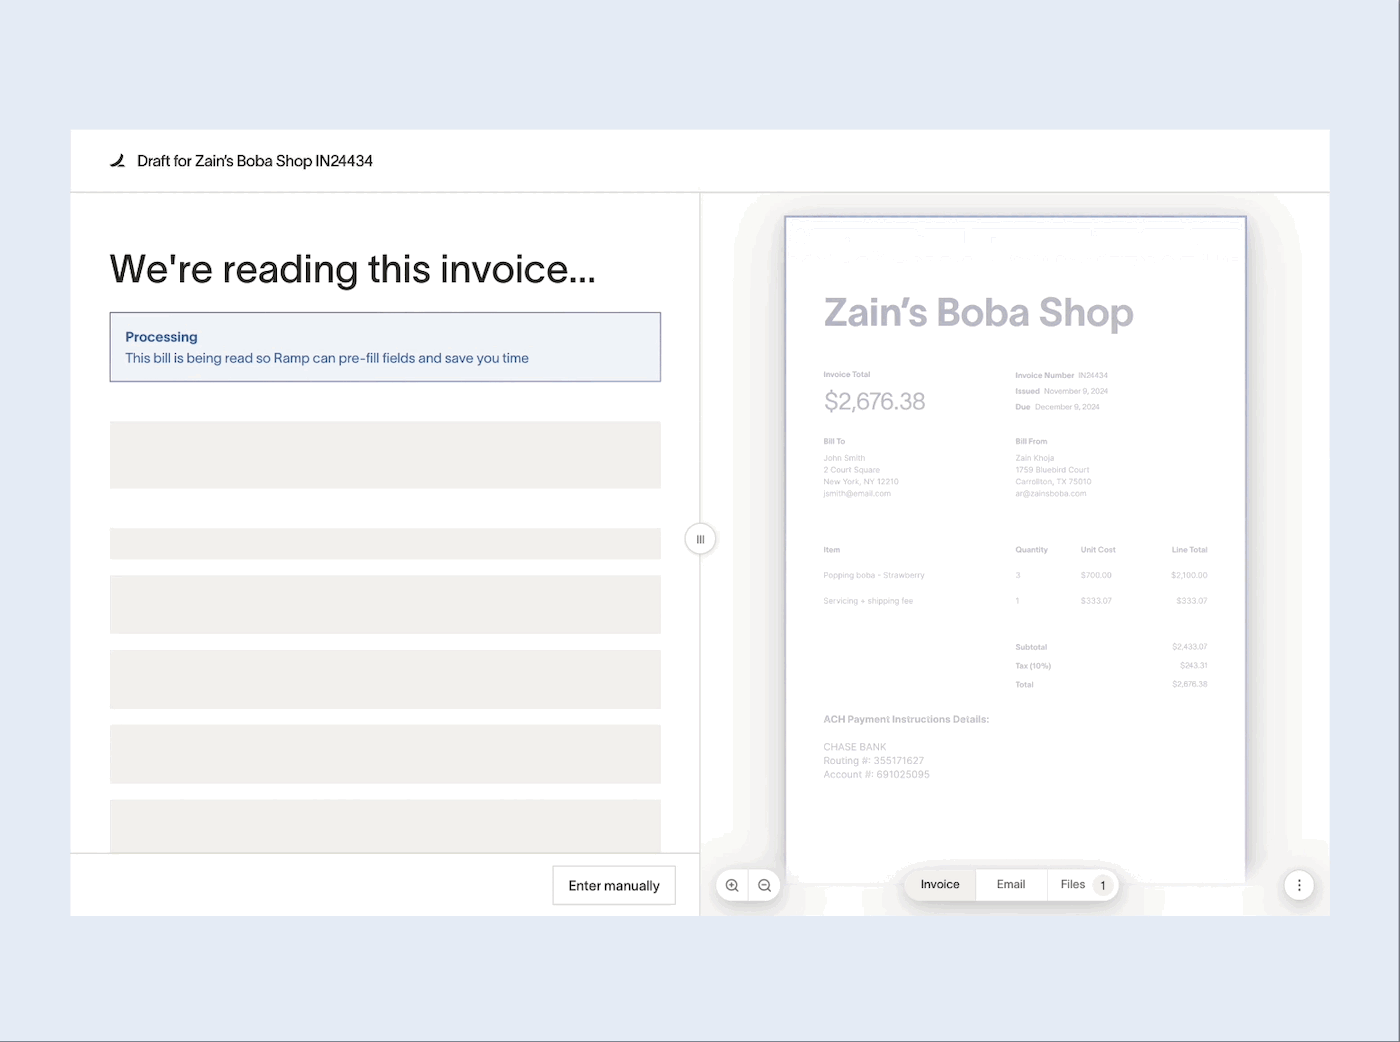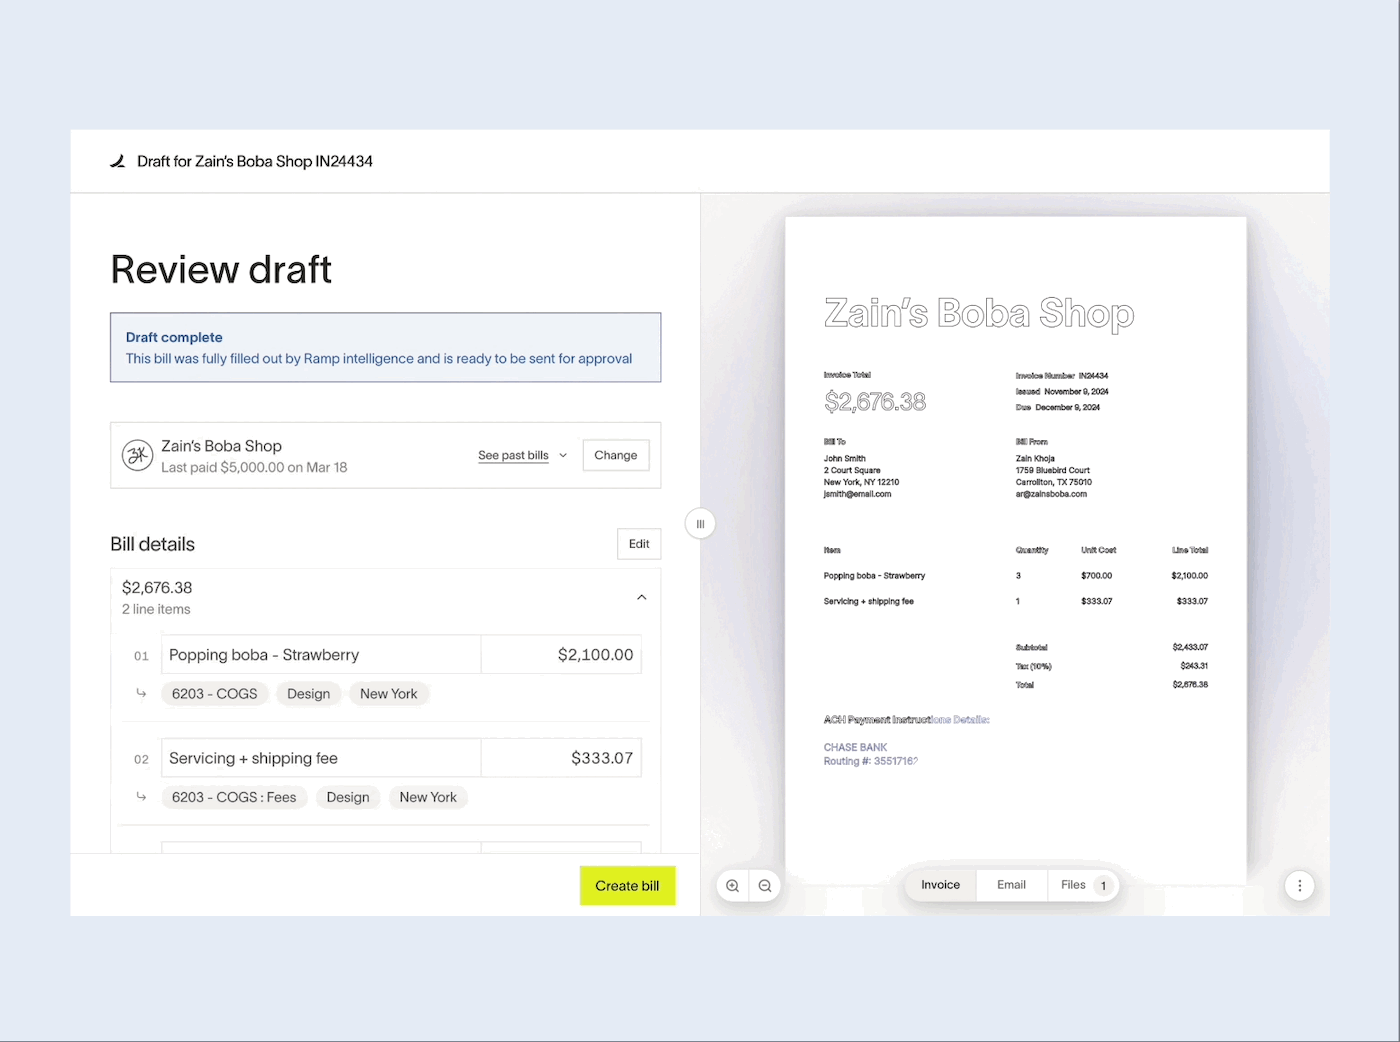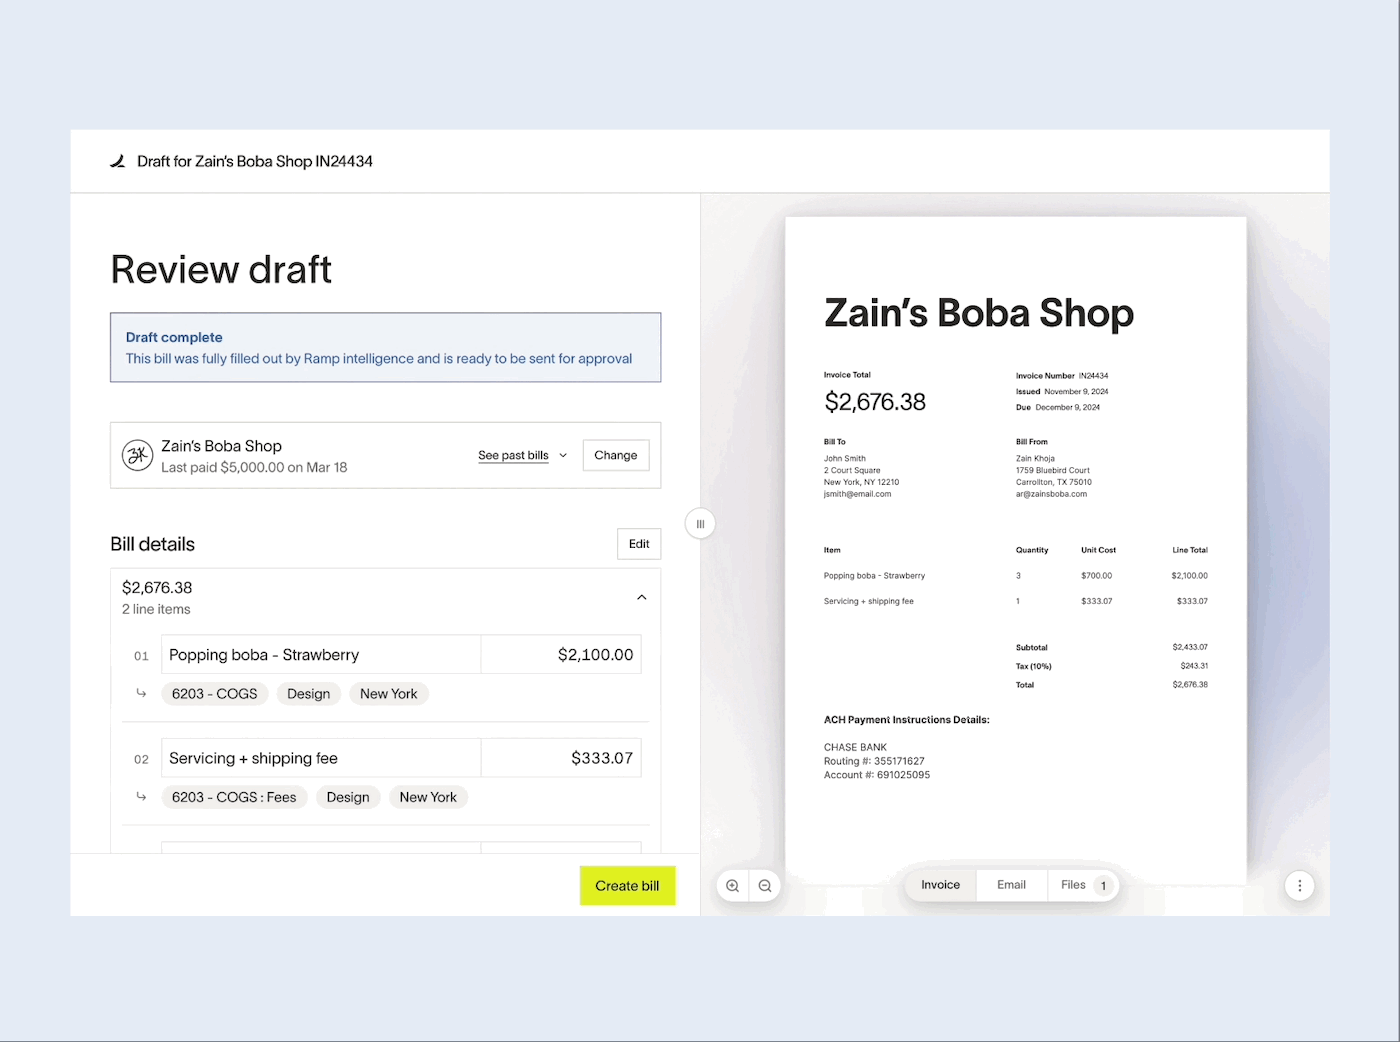
- An invoice arrives in an unexpected format: A rules-based system matches known templates and kicks anything unfamiliar to a person for manual entry. AI reads the document, extracts the line items, and codes it even though it's never seen that vendor's layout.
- A transaction sits between two policy rules: Automation either forces the transaction into whichever rule fires first or flags it as an error. AI weighs the policy language against the specifics of the charge and recommends approve, reject, or escalate with a reason attached.
- A vendor renewal has no clean precedent: A rules-based tool has nothing to match against, so it does nothing until you build a new rule. AI compares the contract to similar past agreements, surfaces the auto-renewal clause, and tells you what's worth questioning.
The pattern holds across every function: Rules cover the cases you predicted, and AI covers the ones you didn't. Your volume of unpredictable cases is what decides how much that second capability is worth to you.
Three signs a finance tool uses genuine AI
Genuine AI shows three traits you can recognize without a data science background. Each one separates a tool that reasons from a tool that just runs a script faster.
It reasons about the situation, not just the rule
Real AI looks at the specifics of a transaction and forms a judgment, rather than checking it against a fixed list. A rules-based tool asks "does this match condition X?" and AI asks "given everything about this charge, what's the right call?"
When a $400 dinner comes in from a sales rep during a conference week, a rules engine either approves it because it's under a cap or flags it because it's over one. AI factors in the event, the attendee count, and the policy language before deciding.
It recommends or decides, and shows its reasoning
Genuine AI commits to an outcome and tells you why it landed there, citing the specific policy or precedent behind the call. A tool that only highlights transactions for you to review hasn't decided anything. It's moved the work around.
The test is whether the tool produces a recommendation you can act on and an explanation you can audit, so a reviewer can confirm the logic in seconds instead of rebuilding it.
It improves as it learns from your corrections
When you override an AI tool's decision, it should factor that correction into future calls without you rewriting a rule. Rules-based automation stays exactly as accurate as the day you configured it until someone edits the logic by hand.
A tool that codes 20% fewer errors after a month of your feedback is learning. A tool that repeats the same mistake until you file a configuration ticket is not.
A vendor whose tool misses any one of these three is selling you automation, and you should price it accordingly.
Three tests to run on a vendor demo
You can confirm all three signs live, during the demo, before you sign anything. Three checks expose the difference between a tool that reasons and one that recites its script:
Give it a case the rules never anticipated
Hand the tool an invoice in a layout it wasn't set up for, or a transaction that fits no existing category. Ask the vendor to walk through what the tool does next, in the live environment rather than a slide. If the honest answer is that someone on your team codes it manually or builds a new rule first, you're looking at automation.
Ask it to explain a decision
Point at one decision the tool just made and ask why. A reasoning tool names the policy clause or the comparable transaction it relied on and states its logic in plain language. If the vendor can only tell you which rule was triggered, the tool isn't interpreting anything, and every gray area will come back to your desk.
Correct it, then watch what changes
Override the tool on a handful of transactions and ask what happens the next time a similar one shows up. A learning tool applies your corrections going forward and gets the next call right without a configuration change. If improving accuracy means opening a ticket to rewrite the rules, you own the intelligence rather than the tool.
Run these three tests on every vendor that claims AI, and the ones selling relabeled automation will tell on themselves in minutes.
How Ramp's AI agents close the loop for finance teams
Rules-based automation runs out exactly where your hardest finance work begins: the unfamiliar invoice, the transaction between two policies, the renewal with no precedent. Each of those is a case the rules never covered, so the exception lands back on your team, and the tool you bought to save time hands the judgment work back to you.
Ramp Intelligence is a portfolio of AI agents that make those calls and cite their work, rather than flagging items for a human to sort out later. The agents run inside a single ledger with full visibility into cards, bills, reimbursements, procurement, and travel, so they reason with context that a bolt-on tool integrated into one corner of your stack can't see. Humans stay in the loop and confirm money movements, but the routine decisions close on their own.
Here's what AI vs. automation in fintech looks like once you're running genuine AI agents with Ramp:
- Policy Agent decides, not just flags: Reads your written policy in plain language, evaluates every transaction, and recommends approve, reject, or escalate with the exact policy clause cited
- AP Agent handles the invoice end to end: Manages ingestion through GL coding, flags fraud, recommends approvals, and learns from your corrections instead of repeating the same miscodes
- Accounting Agent closes the loop on the books: Codes transactions, reconciles, and syncs to your ERP so month-end stops waiting on manual entry
- Procurement Agent reads the fine print: Routes intake, analyzes contracts, and flags auto-renewals before they bill you again
- Every agent works from one source of context: Because the agents share a single ledger across your spend, their decisions reflect the full picture rather than one integration's slice of it.
Try an interactive demo to see the difference, and join the companies that save an average of 5% a year across all spending with Ramp.

FAQs
Automation runs pre-written rules the same way every time, and AI evaluates the inputs and decides, including in cases no rule anticipated. Automation is predictable and static, while AI reasons through context and improves as it learns from corrections. In finance, that's the difference between a tool that stops at anything unfamiliar and one that keeps working.
Neither is better in the abstract, because they solve different problems. Automation is the right fit for high-volume, repetitive tasks with clear rules, like recurring journal entries. AI earns its cost when your work is full of exceptions and judgment calls that no fixed rule covers, which is where most growing finance teams get stuck.
No. A lot of fintech tools marketed as AI are rules-based automation with new branding. The test is whether the tool can handle a case its rules never anticipated, explain its own decisions, and improve from your corrections. If it can't do all three, it's automation.
AI is taking over the repetitive parts of finance work, like coding transactions and first-pass expense review. The judgment stays with people. Controllers and CFOs still own strategy, exceptions, and every decision that moves money, and the shift redeploys finance talent toward higher-value work rather than eliminating the roles.
Run three checks in the demo. Give the tool a case its rules never anticipated, ask it to explain a specific decision and cite the policy behind it, and correct it a few times to see whether it adapts. Genuine AI clears all three, and relabeled automation fails at least one.


“I assumed I would have to choose between speed and control. What I found is that you can have both. A well-designed system takes friction out, for the finance function and for everyone else.”
Justin Webster
CFO, Denver Broncos

“A well-run district should not have to choose between getting work done at the school site and keeping control of the dollars behind it. We're not hiring more people to do more jobs, so we have to be smarter about the process. With Ramp, the purchase, the receipt, and the record stay together from the start. ”
Nick Brizeno
Director of Purchasing, San Marcos Unified School District

“AI is moving faster than the finance context around it. Prices change, models change, and the value is not always obvious from an invoice. We needed enough detail to know which bets deserved more investment — and which ones did not.”
Greg Cooley
Controller, AngelList

“Invoices, cards, tokens. The categories change but the principle doesn't: know where the money is going, remove the work around it, and make sure the spend is worth it.”
Maciej Mylik. Finance
ElevenLabs

“We weren’t trying to retrofit an old finance system. We had a blank canvas, and Ramp gave us the foundation to build a global finance function of the future.”
Justin Dourado
Director of Finance, Othership

“There's just no surprises anymore. No more waiting two months to find out how a job did. We know how it's doing as it's happening.”
Erich Kuss
Financial Systems Manager, Infinity Home Services

“More token spend isn’t proof that AI is working. Less isn’t proof that it isn’t. What matters is whether we’re buying the right level of intelligence for the work. Ramp lets us make that judgment in the same place we manage every other type of spend.”
Cody Nutt
Senior Director of Business Systems, Daxko

“Most banks treat the back office as a cost to keep down. We treat ours as a return to compound, which is why we run it on Ramp. Now we put our clients on Ramp, too.”
Patrick Gaughen
President & COO, Hingham Institution for Savings
