Best no annual fee business credit cards of 2026

- At a glance: Comparing the best no annual fee business credit cards
- 9 best business credit cards with no annual fee
- Best cashback business credit cards with no annual fee
- Best no fee business travel credit cards
- Best small business credit cards with no annual fee
- Best free corporate credit cards
- Why no annual fee cards matter for small businesses
- What rewards and perks do no annual fee business credit cards offer?
- No annual fee vs. fee based business credit cards
- Who can get a no annual fee business credit card?
- How to calculate if paying an annual fee is worth it?
- How to choose the best no fee business credit card
- Get a Ramp business credit card with no annual fee
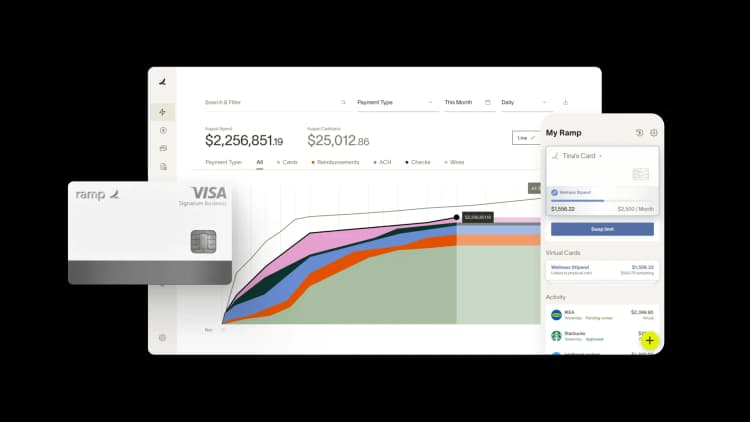
No-annual-fee business credit cards earn rewards or cashback on purchases without charging a yearly fee, giving your company a cost-effective way to manage spending and build credit. These cards combine flexibility with cost control, making them a practical fit for startups and growing businesses that want purchasing power without extra overhead.
Note: The cashback percentages, limits, fees, and other figures mentioned in this article are for illustrative purposes only. They do not represent guaranteed or expected rates. Actual terms, credit limits, rewards, and approval criteria vary by card issuer and may change at any time. Readers should verify current details directly with each issuer before applying.
At a glance: Comparing the best no annual fee business credit cards
No-annual-fee business credit cards help you manage everyday spending and build credit without paying yearly costs. The Ramp Business Credit Card is our top no-annual-fee pick for spend control, with the Ink Business Unlimited and Amex Blue Business Cash strong alternatives for flat-rate rewards.
The table below highlights key rewards, fees, and best-for use cases so you can compare leading business credit cards with no annual fee at a glance:
| Card | Annual fee | Rewards rate | Welcome bonus | Intro APR | Best for |
|---|---|---|---|---|---|
| Ramp Business Credit Card | $0 | Cashback on purchases | None | N/A | Spend control and automated expense management |
| Ink Business Unlimited® | $0 | Flat cashback on all purchases | Cash bonus after meeting spend | 0% intro on purchases | Flat-rate rewards you can pair with Chase Ultimate Rewards |
| Ink Business Cash® | $0 | Elevated cashback on office supplies and telecom | Cash bonus after meeting spend | 0% intro on purchases | Office supply and telecom spend |
| Amex Blue Business Plus | $0 | Membership Rewards points on purchases | Points bonus after meeting spend | 0% intro on purchases | Transferable Membership Rewards points |
| Amex Blue Business Cash | $0 | Elevated cashback up to annual cap | Cash bonus after meeting spend | 0% intro on purchases | Straightforward cash back |
| Capital One Spark Cash Select | $0 | Flat cashback plus travel bonus | Cash bonus after meeting spend | None | International spend, no foreign transaction fees |
| U.S. Bank Triple Cash Rewards | $0 | Tiered cashback on gas, office, telecom, dining | Cash bonus after meeting spend | 0% intro on purchases | Tiered category cash back plus software credit |
| Wells Fargo Signify Business Cash | $0 | Flat cashback on all purchases | Cash bonus after meeting spend | 0% intro on purchases | Unlimited flat-rate cash back with free employee cards |
| BoA Business Advantage Unlimited Cash Rewards | $0 | Flat cashback on all purchases | Cash bonus after meeting spend | 0% intro on purchases | BofA business customers building credit |
9 best business credit cards with no annual fee
Each card below covers its annual fee, APR, rewards, and pros and cons so you can compare where it fits your spending.
Ramp Business Credit Card

- No annual, late, or interest fees: Ramp eliminates all recurring fees, helping businesses save without worrying about hidden costs.
- No personal guarantee required: Approval is based on business financials, not personal credit, allowing founders to build business credit safely.
- Higher, flexible credit limits: Ramp determines limits using company cash flow and balances—often much higher than traditional cards.
- Flat-rate cashback: Earn cashback on every purchase with no category tracking or rotating rewards.
- Automated expense management: Track spend in real time and automate receipt matching through Ramp’s integrated platform.
- Direct accounting integrations: Sync with QuickBooks, Xero, and NetSuite to simplify reconciliation and reporting.
- If your business prioritizes maximizing rewards in specific categories such as travel or dining, Ramp may offer less value.
- Not suitable for sole proprietors: Ramp requires a registered business entity (LLC, LP, or corporation) to qualify.
- No ability to carry a balance: As a charge card, Ramp requires full payment each month, so it’s not ideal for financing purchases.
The Ramp Business Credit Card is a free corporate card with built-in expense management, automated receipt matching, and real-time spend controls. Ramp offers cashback rewards on purchases, with no annual fee, late fees, or foreign transaction fees.
Approval is based on business financials, not personal credit, so there's no personal guarantee required. Ramp also integrates directly with QuickBooks, Xero, and NetSuite to simplify reconciliation, making it a strong fit for growing businesses that want rewards plus operational efficiency.
Chase Ink Business Cash Credit Card

- If you spend a lot on office supplies or on internet, phone and cable services, this card caters to that
- Cardholders are automatically checked for a credit line increase every 6 months or sooner
- The card offers 5% cash back on Lyft rides through September 2027
- Earn 1% cash back on all other purchases with no limit
- Bonus cash back categories are capped at $25,000 in combined purchases per account anniversary year
- A foreign transaction fee of 3% is charged on purchases made outside the U.S.
- Cash back rewards are limited to 1% on all purchases outside the bonus categories
- 10% Business Relationship Bonus is only available if you have a Chase Business Checking account on your first card anniversary
The Ink Business Unlimited delivers unlimited flat-rate cashback on every purchase with no annual fee. New cardholders can earn a cash bonus after meeting a minimum spend threshold in the first three months, plus an introductory 0% APR on purchases.
This card suits businesses that want predictable rewards without tracking categories. The flat-rate structure makes it easy to forecast value across diverse spending.
Chase Ink Business Cash Credit Card
- If you spend a lot on office supplies or on internet, phone and cable services, this card caters to that
- Cardholders are automatically checked for a credit line increase every 6 months or sooner
- The card offers 5% cash back on Lyft rides through September 2027
- Earn 1% cash back on all other purchases with no limit
- Bonus cash back categories are capped at $25,000 in combined purchases per account anniversary year
- A foreign transaction fee of 3% is charged on purchases made outside the U.S.
- Cash back rewards are limited to 1% on all purchases outside the bonus categories
- 10% Business Relationship Bonus is only available if you have a Chase Business Checking account on your first card anniversary
The Ink Business Cash earns elevated cashback on office supply stores, internet, cable, and phone services, plus a smaller bonus on gas and dining. Bonus categories are capped annually, with a flat rate on all other purchases.
It's a strong fit if you're setting up an office or running a business with steady telecom and supply expenses. The intro APR period also helps with larger immediate purchases.
American Express Blue Business Plus

- No annual fee: Access Amex benefits without annual costs.
- 2X Membership Rewards points: Earn double points on the first $50,000 spent annually, then 1X points thereafter.
- Access to American Express benefits: Utilize Amex's expense management tools and customer service.
- 2.7% foreign transaction fee: Adds costs for international purchases.
- Points cap at $50,000 annually: After reaching the cap, rewards rate decreases.
- Limited flexibility for higher spending: May not suit businesses with spending over $50,000 per year.
- Few business-specific perks beyond points: Lacks extensive business management features.
The Amex Blue Business Plus earns Membership Rewards points on the first chunk of annual spend, then a base rate after that. Points can be transferred to airline and hotel partners or redeemed for travel, gift cards, and statement credits.
This card works best if you want flexible point redemptions over straight cashback. There's no annual fee, and an intro APR helps stretch larger purchases.
American Express Blue Business Cash Card

- 0% intro APR for 12 months
- Earn 2% cash back on eligible purchases (up to $50,000 per year)
- No annual fee
- Flexible spending limit
- 2% cash back is capped at $50,000 in annual purchases
- Foreign transaction fee applies
- Must be an Amex-accepting business
The Amex Blue Business Cash offers a higher cashback rate on the first tier of annual spending, then a base rate after the cap. Cashback is automatically credited to your statement, simplifying redemption.
It's a solid pick for newer businesses or lower-spend operations that can fully capture the elevated rate without exceeding the cap. The card also includes an intro APR on purchases.
Capital One Spark Cash Select

- No annual fee
- Introductory APR supports large purchases
- No foreign transaction fees
- No category-specific rewards bonuses
- Limited overall rewards potential for specific spenders
The Capital One Spark Cash Select earns flat-rate cashback on every purchase, with a bonus rate on hotels and rental cars booked through Capital One Business Travel. There's no annual fee and no foreign transaction fees.
If you want simple rewards plus travel perks without paying for premium status, this card delivers a balanced mix. Approval typically requires good to excellent credit.
U.S. Bank Business Triple Cash Rewards Visa Business Credit Card

- High cashback potential on qualifying purchases
- No annual fee
- Statement credit for software subscriptions
- Foreign transaction fees apply
- Bonus categories may not suit all businesses
The U.S. Bank Triple Cash Rewards earns elevated cashback at gas stations, office supply stores, restaurants, and on cell phone services, plus a base rate on other purchases. New cardholders can earn a cash bonus after meeting a spend threshold, plus an intro 0% APR period.
This card fits teams that spend across several common business categories. The intro APR window helps with balance transfers or large initial expenses.
Wells Fargo Signify Business Cash Card
- 0% intro APR on purchases and balance transfers for nine months
- No annual fee and free employee cards
- $500 cash rewards bonus when you spend $5,000 for your business in the first 3 months
- Earn 2% unlimited cash rewards without caps or spending categories
- No special category multipliers
- Limited travel and premium benefits
The Wells Fargo Signify Business Cash earns flat-rate cashback on every purchase with no caps or categories to track. It includes a 0% intro APR on purchases for 12 months, plus free employee cards.
It's well-suited for high-volume spenders who want unlimited rewards on all transactions. The straightforward structure removes the need to plan around bonus categories.
Bank of America Business Advantage Unlimited Cash Rewards Secured Credit Card

- Unlimited 1.5% cashback on all categories
- Option to upgrade to an unsecured card
- No annual fee
- Requires deposit as collateral for your line of credit
- 3% foreign transaction fee
- No intro APR offer
The BoA Business Advantage Unlimited Cash Rewards card earns flat-rate cashback on every purchase with no annual fee. Eligible Bank of America business customers may earn an additional rewards boost through the Preferred Rewards for Business program.
This card rewards loyalty if you already bank with Bank of America. As a secured card, it's built to help newer businesses establish credit rather than to maximize short-term perks. Pairing it with a dedicated business banking account can further strengthen your overall financial foundation.
Best cashback business credit cards with no annual fee
Cashback is popular for small business credit cards with no annual fee because it offers straightforward value without redemption complexity. You can think of cashback cards in two main groups:
- Flat-rate cards: Earn the same percentage on every purchase
- Tiered/category cards: Earn higher rates in specific spending categories
Some of the best cash back business credit cards with no annual fee are:
- Ink Business Cash® Credit Card: Best for category bonuses on office supplies and telecom services. Bonus-category earnings are capped annually, so monitor spend to maximize value before dropping to the base rate.
- American Express Blue Business Cash Card: Best for a higher cashback rate up to an annual spending threshold. After hitting the cap, earnings drop to a flat base rate.
- Wells Fargo Signify Business Cash Card: Best for unlimited flat-rate cashback with no category tracking. The straightforward structure makes it easy for high-spend businesses to predict rewards.
- Bank of America Business Advantage Customized Cash Rewards Mastercard: Best for choosing your own bonus category, such as gas, office supplies, travel, or business consulting. You can change your category each month to match shifting expenses.
Best no fee business travel credit cards
Some business credit cards with rewards and no annual fee still offer solid travel benefits, including no foreign transaction fees. Look for travel-specific earning rates and built-in travel insurance alongside that fee waiver.
- Bank of America Business Advantage Travel Rewards World Mastercard: Earns flat-rate points on every purchase, redeemable for statement credits against travel and dining purchases. There are no foreign transaction fees, making it useful for international travel.
- Capital One Spark Cash Select: Earns bonus cashback on hotels and rental cars booked through the Capital One Travel portal, plus a flat rate on other purchases. The card carries no foreign transaction fees.
Discover Ramp's corporate card for modern finance
Best small business credit cards with no annual fee
Small business owners and startups benefit from a small business credit card with no annual fee because it minimizes costs while building credit history. Key advantages include:
- Lower barrier to entry for new businesses
- Helps separate personal and business expenses
- Builds your business credit profile over time
Here are some of the top picks:
- American Express Blue Business Cash Card: Good for startups with moderate monthly spend. The elevated cashback rate up to an annual cap aligns well with smaller budgets.
- Ink Business Unlimited® Credit Card: Solid for businesses that want simple, predictable rewards without tracking categories. Flat-rate cashback works across all spending types.
- Capital on Tap Business Credit Card: Offers a soft credit pull for prequalification and a quick approval process. It's accessible for newer businesses that want to check eligibility without affecting personal credit.
Best free corporate credit cards
Corporate cards differ from small business cards in a few key ways: they typically don't require a personal guarantee, offer higher limits, and include built-in spend management tools. They're often the best free business credit cards for growing companies that need more than rewards.
- Ramp Card: Ramp charges no fees, ever, and pairs the card with built-in expense management, automated accounting integrations, and real-time spending controls. Finance teams use Ramp to eliminate manual expense tracking and close books faster.
- Brex Card: Designed for startups and venture-backed companies, with no personal guarantee required. Approval is based on business cash balances and financials.
- BILL Divvy Corporate Card: Combines a corporate card with budgeting and expense management features built into the platform. It's useful for teams that want spend controls tied to specific budgets.
Why no annual fee cards matter for small businesses
No-annual-fee business credit cards give small businesses a way to manage everyday spending and build credit without adding fixed costs. For startups and growing teams, avoiding recurring fees helps preserve cash flow while still providing access to purchasing power and basic rewards.
The savings add up: the CFPB's own market survey found average annual fees ran about $94 for cards from smaller issuers and $157 for the largest card issuers, so skipping the fee altogether keeps that cost entirely off your books.
Most no-fee cards focus on simple earning structures, such as flat-rate cashback or limited category bonuses, making rewards easier to track month to month. Some issuers also evaluate business revenue or cash flow in addition to personal credit, which can make these cards more accessible to newer companies.
If your goal is to simplify spend management while earning rewards, no-fee cards strike a strong balance between savings and flexibility.
What rewards and perks do no annual fee business credit cards offer?
No-annual-fee business cards typically offer three reward types: cashback, points or miles, and welcome bonuses. Understanding each helps you compare options on equal footing.
Cashback rewards
Cashback returns a percentage of each purchase as a statement credit or deposit. It's the most straightforward reward type because there's no need to calculate point values or hunt for redemption deals.
Points and miles
Points and miles are earned per dollar spent and redeemed for travel, gift cards, or transferred to airline and hotel partners. They can offer higher value than cashback, but only if you're willing to optimize your rewards redemption.
Welcome bonuses
Sign-up bonuses require meeting a minimum spend within the first few months of opening the card. They can deliver significant up-front value, often worth several hundred dollars in cash or points.
Intro APR offers
An intro APR is a temporary low or zero interest rate on purchases or balance transfers, usually lasting 9–15 months. These 0% APR business credit cards and 0% interest business credit cards are useful for financing larger purchases or consolidating existing card debt. If you're weighing whether to use a card for larger financing needs, it's also worth understanding the basics of debt financing before committing.
Employee cards at no extra cost
Most no-fee business credit cards let you add employee cards without additional fees. This centralizes spending and tracking, making it easier to monitor company expenses.
Purchase protection and extended warranty
Some cards offer protection against damage or theft on recent purchases and extend manufacturer warranties on eligible items. These benefits add value without raising your costs.
Expense management and accounting integration
Cards with built-in expense tools or accounting software integrations save hours on reconciliation. With Ramp, 90% of transactions are auto-coded on receipt and sync straight to QuickBooks, Xero, and NetSuite, so nothing waits for month-end reconciliation. Ramp also offers automated receipt matching and real-time spend visibility, so transactions sync directly into your accounting system before spend even happens.
No annual fee vs. fee based business credit cards
Business credit cards with annual fees typically bundle in additional benefits. Card issuers use rewards, larger bonuses, and premium perks to offset the yearly cost, though the actual value depends on how your business spends.
| Factor | No-annual-fee cards | Fee-based cards |
|---|---|---|
| Up-front cost | None | Annual fee charged |
| Rewards rates | Typically lower | Often higher |
| Premium perks | Limited | Travel credits, lounge access, concierge |
| Best for | Cost-conscious, low-to-moderate spend | High spenders who can maximize perks |
Paying an annual fee can make sense if you'll fully use the card's premium perks, such as lounge access, statement credits, or elevated rewards in your top spending categories. If your spend is moderate or your team values simplicity, a free business card usually delivers more net value.
Run the math before you decide: if you spend $30,000 a year and earn 2% back, that's $600 in rewards, so a $95 annual fee only pays off if the card's extra perks and higher rate clear that $95 gap (figures illustrative).
Consider ongoing fees that can add up
A no-annual-fee card removes one major cost, but other charges can still affect your total. Watch for:
- Foreign transaction fees: Many cards charge 2%–3% on international purchases. If you spend abroad, choose a business card with no foreign transaction fees
- Late payment fees: Missing a due date can trigger fees and a penalty APR
- Balance transfer fees: If you plan to consolidate debt, check the transfer fee, usually a percentage of the balance
- Employee cards: Some issuers charge for additional cards, while others include them free
Ramp removes many of these extra costs. There are no foreign transaction fees, late fees, or employee card fees, which keeps monthly spending more predictable.
Who can get a no annual fee business credit card?
Eligibility varies by issuer, but most no-fee business credit cards share a few common requirements. Knowing what you'll need before applying helps protect your credit and improve approval odds.
Credit score requirements
A 600 credit score puts you in the fair-credit range, where some no-annual-fee business cards will approve you, though usually with a lower limit and fewer perks. Most business credit cards require good to excellent personal credit, typically a FICO score of 670 or higher; cards aimed at fair credit may approve scores in the 580–669 range.
Business documentation you need
Issuers typically ask for:
- Your EIN (or SSN if you're a sole proprietor)
- Legal business name and structure
- Annual business revenue
- Time in business
- Estimated monthly spend
Business credit cards with no personal guarantee
Some corporate cards, like Ramp and Brex, don't require a personal guarantee or a personal credit check. Approval is based on business financials, such as cash balance, revenue, and spending patterns, rather than your personal credit. These cards are best if you want to protect personal credit while building a business credit profile. It's also worth understanding business credit card liability before you apply, so you know exactly what you're on the hook for.
How to calculate if paying an annual fee is worth it?
A fee-based card is worth it only when its rewards and perks clearly outweigh what you'd give up by choosing a free card instead. Use this simple framework to weigh a fee-based card against a free one:
- Add up rewards value: Estimate your annual rewards based on realistic spending across the card's earning categories
- Add perks value: Assign a dollar value to benefits you'll actually use, like travel credits or lounge access
- Compare to the annual fee: If total value clearly exceeds the fee, the card may be worth it
- Consider opportunity cost: A no-fee card lets you keep every dollar of rewards without breaking even first
When the math doesn't clearly favor a fee-based card, a no-annual-fee option is often the smarter, lower-risk default.
How to choose the best no fee business credit card
Choosing the right card starts with how your company spends and what value you expect in return. Use this five-step framework to narrow your options.
- Identify your top spending categories: Review where your business spends most, such as office supplies, travel, advertising, software, or telecom. Match those categories to cards that offer elevated rewards on what you already buy.
- Decide between cashback and points: Cashback is simpler and easier to value, whereas points can deliver higher returns if you redeem strategically through travel partners. Choose based on how much time you're willing to invest in optimizing rewards.
- Evaluate welcome bonus spend requirements: Make sure you can meet the minimum spend through normal business activity. Don't overspend just to earn a bonus. The math rarely works in your favor.
- Consider expense management needs: If you need spend controls, receipt tracking, and accounting integrations, look for cards with built-in tools. Ramp combines a free corporate card with automated expense workflows so you don't need separate software.
- Check your approval odds: Some issuers offer prequalification with a soft credit pull. Check before applying so a hard inquiry doesn't ding your credit score unnecessarily.
Get a Ramp business credit card with no annual fee
If you're looking for a fee-free business card, consider Ramp. A Ramp Business Credit Card comes with no annual fees, late fees, card replacement fees, or interest. Plus, earn cashback on purchases.
U.S. businesses just need an EIN and at least $25,000 in a business bank account to sign up for Ramp. We don't need your SSN or business credit score. Plus, our e-commerce underwriting program may help you get a higher credit limit than a traditional credit card.
Ramp's spend management software and real-time insights also help you manage business expenses and get control of your cash flow. We also empower employees to spend responsibly with customizable spend limits and vendor controls on unlimited free employee business cards.

FAQs
Most business credit cards require your SSN for a personal credit check and personal guarantee. Some corporate cards, like Ramp and Brex, use business financials instead and don't require a personal guarantee, so you can apply with just your EIN and business details.
Yes. Several no-annual-fee business credit cards offer 0% intro APR periods on purchases, typically lasting 9–15 months after account opening, and some extend that to balance transfers too.
A 600 credit score falls in the fair-credit range (580–669), where some issuers approve applications but usually with lower limits and fewer perks. Most no-fee cards require good to excellent credit, typically 670 or higher.
Yes, you can hold multiple business credit cards from different issuers at once. Many businesses pair a flat-rate card with a category-bonus card to maximize rewards across spending types.
Some issuers report business card activity to commercial credit bureaus, which builds your business credit profile over time. Check whether the card reports to Dun & Bradstreet, Experian Business, or Equifax Business before applying.


“A well-run district should not have to choose between getting work done at the school site and keeping control of the dollars behind it. We're not hiring more people to do more jobs, so we have to be smarter about the process. With Ramp, the purchase, the receipt, and the record stay together from the start. ”
Nick Brizeno
Director of Purchasing, San Marcos Unified School District

“Invoices, cards, tokens. The categories change but the principle doesn't: know where the money is going, remove the work around it, and make sure the spend is worth it.”
Maciej Mylik. Finance
ElevenLabs

“There's just no surprises anymore. No more waiting two months to find out how a job did. We know how it's doing as it's happening.”
Erich Kuss
Financial Systems Manager, Infinity Home Services

“More token spend isn’t proof that AI is working. Less isn’t proof that it isn’t. What matters is whether we’re buying the right level of intelligence for the work. Ramp lets us make that judgment in the same place we manage every other type of spend.”
Cody Nutt
Senior Director of Business Systems, Daxko

“Most banks treat the back office as a cost to keep down. We treat ours as a return to compound, which is why we run it on Ramp. Now we put our clients on Ramp, too.”
Patrick Gaughen
President & COO, Hingham Institution for Savings

“Browserbase builds infrastructure so AI agents can do real work. Ramp is doing the same for finance. It’s not another tool. It’s a system purpose-built for AI-driven finance, and that’s why we chose Ramp as our financial operating system from day one.”
Paul Klein IV
Founder & CEO, Browserbase

“We used to pay up to $20k a year for our AP platform. With Ramp, we’re earning back well over that amount. That's money that belongs to the mission now, not to the back-office software.”
Heidi Coffer
Chief Financial Officer, Boys & Girls Clubs of San Francisco

“The tricky thing about corporate travel policy is timing. We didn't need a stricter policy. We needed the policy to show up earlier. With Ramp Travel, it finally does.”
Keith Frantz
Director of Enterprise Risk Management, Prosper
