
- Business credit card issuers that report to Dun & Bradstreet
- Direct D&B reporting vs. SBFE reporting
- Do all business credit cards report to D&B?
- 10 business credit cards that report to Dun & Bradstreet
- What about secured business credit cards that report to D&B?
- Why your business should use a business credit card
- How business credit card issuers report to credit bureaus
- How Dun & Bradstreet determines your business credit score
- How to check if your business credit card is reporting to D&B
- Vendors that report to Dun & Bradstreet
- How Marqeta optimized its card program for stronger credit management
- Build credit with a Ramp Business Credit Card
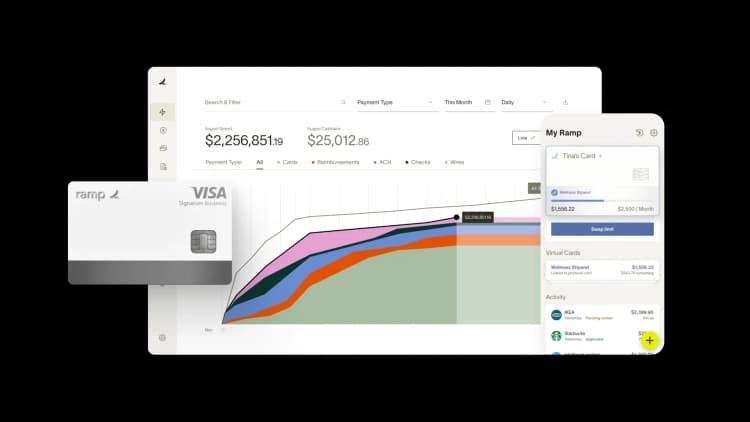
If you're trying to build your company's D&B credit profile, the card in your wallet may not be doing the work you think it is. Reporting to Dun & Bradstreet is voluntary, and most issuers don't do it by default. Unlike other business credit bureaus, D&B focuses solely on business credit and issues the widely used D-U-N-S number, which many suppliers and government agencies require.
One of the fastest ways to build business credit is by using a business credit card that reports payment activity and account history directly to D&B, strengthening your company's credit profile and improving your ability to secure loans and negotiate better vendor terms.
Here are some credit card issuers that report to Dun & Bradstreet and 10 business credit cards to consider.
Note: The cashback percentages, limits, fees, and other figures mentioned in this article are for illustrative purposes only. They do not represent guaranteed or expected rates. Actual terms, credit limits, rewards, and approval criteria vary by card issuer and may change at any time. Readers should verify current details directly with each issuer before applying.
Business credit card issuers that report to Dun & Bradstreet
Several major issuers report to D&B, but the how matters as much as the who: some send data directly to Dun & Bradstreet, while others only route it through the Small Business Financial Exchange (SBFE). Here's a quick overview of the companies that report to Dun and Bradstreet and how they do it.
| Issuer | Reports to D&B | Experian | Equifax | Reports to personal credit |
|---|---|---|---|---|
| Ramp | Direct | No | No | No |
| Brex | Direct | — | — | No |
| Capital One (Spark) | Direct | Yes | Yes | No |
| Chase (Ink) | Direct | Yes | Yes | No |
| Bank of America | Via SBFE | — | — | No |
| U.S. Bank | Direct + SBFE | No | No | No |
| Corpay One | Direct | Yes | Yes | Personal guarantee |
| FNBO (secured) | Direct | Yes | Yes | No |
| AtoB | Direct | — | — | No |
| American Express | Only if seriously delinquent | Yes | Yes | No |
Not every issuer that reports to D&B does so in a way that actively builds your profile, so it's worth knowing who reports to Dun and Bradstreet directly versus through the cooperative before you apply.
What gets reported to Dun & Bradstreet?
When a business credit card issuer reports to Dun & Bradstreet, they share details about your business's trade credit activity. This includes your payment history with vendors, outstanding balances, credit utilization, account age, and any public records such as liens or bankruptcies.
This information contributes to your D&B credit file and helps generate your PAYDEX score, which lenders, suppliers, and insurance providers use to assess your company's creditworthiness.
A strong D&B profile is one of the best ways to improve your business's access to financing, negotiate better vendor terms, and strengthen trust with business partners. But keep in mind that not all issuers report positive activity as some only report negative events like late payments or defaults. So, it's important to choose a business credit card that helps you actively build your credit profile.
And while many business credit cards require a personal guarantee, the reporting to D&B is separate from your personal credit history, helping your business establish its own independent credit footprint.
Direct D&B reporting vs. SBFE reporting
Not all D&B reporting is equal: direct reporting sends your payment data straight to Dun & Bradstreet, while SBFE reporting routes it through the Small Business Financial Exchange first, which can delay or limit what reaches your D&B file.
Direct issuers such as Ramp, Brex, FNBO, and AtoB send data to D&B at the end of each billing cycle. SBFE issuers such as Bank of America and U.S. Bank route data through the cooperative, so the timing and coverage of what lands on your file aren't guaranteed. That difference matters most when you're timing a loan or vendor application and need recent activity to show up on schedule. Keep in mind that SBFE names only some of its 140-plus members, and several issuers that report directly to the bureaus (including Capital One and American Express) also contribute data through SBFE, so these groupings reflect how each issuer's reporting is commonly described rather than a strict either/or split.
| Direct D&B reporting | SBFE reporting |
|---|---|
| Data goes straight to D&B | Data routes through the SBFE cooperative first |
| Posts at the end of each billing cycle | Timing and coverage aren't guaranteed |
| Ramp, Brex, FNBO, AtoB | Bank of America, U.S. Bank |
How long before a new account shows up on your D&B file?
A tradeline from a direct-reporting issuer usually appears within a billing cycle or two of account opening, while SBFE-routed cards can take longer because the data passes through the cooperative before it reaches D&B. D&B doesn't publish a fixed timeline, so when timing matters, a direct-reporting card is the safer choice because your activity reaches your file without an extra processing step in between.
Do all business credit cards report to D&B?
Not all business credit cards report to Dun & Bradstreet or other business credit bureaus. Some cards report only to D&B, some to Experian Business or Equifax Business, and some may not report positive payment activity at all—only negative activity.
If your business credit card doesn't report to D&B, your positive payment history won't appear on your D&B file, meaning you miss out on building your PAYDEX score. Since D&B is one of the most widely used business credit bureaus, especially among lenders and vendors, many business owners prioritize building a strong D&B profile.
That said, not all lenders or partners rely solely on D&B reports. Some providers accept Experian or Equifax Business credit reports when evaluating creditworthiness, so it's smart to build your business credit across multiple bureaus.
A good business credit score can only improve your chances of qualifying for loans, negotiating better payment terms with vendors, and attracting investors or insurers. Even if you're not looking for financing right now, establishing a strong credit history can open doors down the line. Keep in mind that "reports to D&B" can mean direct reporting or reporting via the SBFE, as covered earlier in this article.
Why not all issuers report to D&B?
Reporting is voluntary and can cost issuers money. Not all card providers prioritize helping businesses build credit profiles as some focus purely on offering spending tools or rewards. Even when they do report, business credit card issuers often emphasize negative data rather than positive payment history.
10 business credit cards that report to Dun & Bradstreet
Here are some business credit cards that report to Dun & Bradstreet:
- Ramp Business Credit Card
- Capital One Spark 1.5% Cash Back Business Credit Card
- Capital One Spark Miles for Business
- Capital One Venture X Business Card
- Bank of America Business Advantage Customized Cash Rewards Credit Card
- U.S. Bank Business Platinum Card®
- U.S. Bank Business Leverage® Visa Signature® Card
- U.S. Bank Triple Cash Rewards Visa® Business Card
- Corpay One Mastercard
- FNBO Business Edition® Secured Mastercard® Credit Card
Here's a closer look at each of these business credit cards, including their reporting practices and key offerings:
1. Ramp Business Credit Card
Reports directly to D&B (not to personal bureaus)
The Ramp Business Credit Card is a charge card that reports directly to Dun & Bradstreet. It doesn't report to personal credit bureaus and doesn't require a personal guarantee, making it appealing for businesses that want to separate business credit from personal liability.
Ramp's corporate card also includes expense management and vendor controls that help businesses manage spending, which indirectly strengthens credit profiles by encouraging responsible usage. Ramp offers up to 20x higher credit limits than traditional business credit cards, giving you more room to spend without straining utilization.
Some of its key features include:
- Ramp offers cashback rewards on purchases
- Up to over $350,000 in partner offers
- Advanced expense management tools
- No annual fee or foreign transaction fees
- Accepted in 200+ countries through the Visa global network
Discover Ramp's corporate card for modern finance
2. Capital One Spark 1.5% cash select business credit card
Reports directly to D&B, Experian, and Equifax
The Capital One Spark 1.5% Cash Select Business Credit Card reports to Dun & Bradstreet, Experian, and Equifax.
The card offers a simple cashback program with flat-rate cashback on purchases ensures consistent rewards without the need to track spending categories. However, the flat rewards structure doesn't include bonus categories, which may be less appealing for businesses that spend heavily in areas where other cards offer higher rewards.
Some of its key features include:
- No annual fee
- Cashback on purchases
- Free employee cards with spending controls
- No foreign transaction fees
3. Capital One Spark Miles for Business
Reports directly to D&B, Experian, and Equifax
The Capital One Spark Miles for Business is a versatile card offering miles on purchases with no annual fee for the first year and no foreign transaction fees. Miles can be redeemed for travel, making this card a strong fit for businesses with regular travel expenses.
The annual fee, waived for the first year, may not appeal to all, and businesses focused solely on cashback rather than travel might prefer other options. This card reports to Dun & Bradstreet, Experian, and Equifax as well.
Some of its key features include:
- $0 annual fee for the first year, then $95
- Miles on purchases
- No foreign transaction fees
- Transfer miles to travel partners
4. Capital One Venture X Business Card
Reports to D&B, Experian, and Equifax (business credit bureaus only, not personal credit)
The Capital One Venture X Business Card offers premium travel perks alongside a simple rewards structure, earning miles on every purchase with no foreign transaction fees. Benefits like access to Capital One Lounges make it a strong option for businesses that travel often. However, smaller businesses may struggle to justify its high annual fee, especially those with limited travel needs.
Some of its key features include:
- $395 annual fee
- Miles on purchases
- Premium travel perks, including lounge access
- No foreign transaction fees
5. Bank of America Business Advantage Customized Cash Rewards
Reports to D&B via SBFE
The Bank of America Business Advantage Customized Cash Rewards Credit Card reports to Dun & Bradstreet via the SBFE, along with Equifax and Experian.
This card offers customizable cashback categories and a 0% introductory APR, making it attractive for businesses looking to manage expenses while building a credit profile.
Some of its key features include:
- No annual fee
- 0% introductory APR on purchases for 7 billing cycles, then 16.74%–26.74% (variable)
- Cashback on purchases with category customization
- $50,000 annual cap on 3% and 2% rewards
6. U.S. Bank Business Platinum Card
Reports to D&B and SBFE, but not Experian or Equifax
The U.S. Bank Business Platinum Card® reports to Dun & Bradstreet and SBFE, but not Experian or Equifax. This card focuses on providing a long 0% introductory APR for purchases and balance transfers. With no annual fee, it is a cost-effective option for maintaining financial flexibility.
However, the card lacks a rewards program, meaning businesses won't earn cashback or points on their purchases. It also has a balance transfer fee and a relatively high standard APR after the introductory period.
Some of its key features include:
- No annual fee
- 0% introductory APR on purchases and balance transfers for 12 billing cycles, then 16.24%–25.24% (variable)
- Fraud protection and security tools
- Online account management
7. U.S. Bank Business Leverage Visa Signature Card
Reports to D&B and SBFE, but not Experian or Equifax
The U.S. Bank Business Leverage® Visa Signature® Card also reports to Dun & Bradstreet and SBFE, but not Experian or Equifax. This card is designed for businesses with varied spending, offering higher rewards on purchases in the top two categories each month. It also includes travel benefits such as no foreign transaction fees.
The $95 annual fee is waived for the first year. Rewards are capped annually, which could limit the earning potential for businesses with substantial spending in multiple categories.
Some of its key features include:
- $0 annual fee for the first year, then $95
- Bonus rewards on the top two spending categories each month
- No foreign transaction fees
- Employee cards with spending controls
8. U.S. Bank Triple Cash Rewards Visa Business Card
Reports to D&B and SBFE, but not Experian or Equifax
The U.S. Bank Triple Cash Rewards Visa® Business Card is a no-annual-fee option offering cashback on purchases in categories like gas, restaurants, and office supply stores. It also features a long 0% introductory APR period.
The card does include a 3% foreign transaction fee, and its cashback rewards are limited to specific spending categories, which may not suit businesses with diverse spending patterns. This card reports to Dun & Bradstreet and SBFE, but not Experian or Equifax.
Some of its key features include:
- No annual fee
- $750 cash back after spending $6,000 in the first 180 days
- 0% introductory APR on purchases and balance transfers for 12 billing cycles, then 17.24%–26.24% (variable)
- Cashback on eligible purchases in specific categories
- $100 annual software credit for subscriptions
9. Corpay One Mastercard
Reports directly to D&B, Experian, and Equifax (personal guarantee required)
The Corpay One Mastercard reports to Dun & Bradstreet, Equifax, and Experian. It requires a personal guarantee, where your personal credit is checked (specifically through Experian Consumer) during the application process.
This card offers integrated payment and expense tracking tools to streamline operations for small and medium-sized businesses. It also has no annual fee, adding to its cost-effectiveness. However, the card's full functionality may depend on integration with the Corpay One platform, which may not appeal to businesses already using other management tools.
Some of its key features include:
- No annual fee
- Cashback on purchases
- Expense management and payment tools
- No foreign transaction fees
10. FNBO business edition secured Mastercard
Reports directly to D&B, Experian, and Equifax, giving you three-bureau coverage from a single secured card
The FNBO Business Edition® Secured Mastercard® reports to Dun & Bradstreet, Equifax, and Experian. You set your own credit limit with a single security deposit between $2,000 and $10,000, making it a flexible option for startups, entrepreneurs, and established businesses looking to enhance their creditworthiness.
While it doesn't offer rewards, the card's primary appeal lies in its ability to support long-term credit growth.
Some of its key features include:
- Security deposit from $2,000 to $10,000 sets your credit limit
- Helps build and strengthen business credit
- Annual fee of $39
- No rewards or introductory APR
What about secured business credit cards that report to D&B?
Secured business credit cards report to D&B just like unsecured cards. Instead of requiring a personal guarantee, they use a cash deposit as collateral to back the credit line. Examples include Bank of America Business Advantage Unlimited Cash Rewards Mastercard Secured, Capital One Quicksilver Secured Cash Rewards Credit Card, and Truist Enjoy Cash Secured Credit Card.
Two options stand out here: the FNBO Business Edition Secured Mastercard, which reports to D&B, Experian, and Equifax from one secured card, and the Valley Visa Secured Business Card, which requires a deposit at 110% of your desired limit up to $25,000 and reports to the major business credit bureaus.
The bottom line: secured cards build your D&B credit the same way unsecured cards do.
Why your business should use a business credit card
Beyond building your business credit score and improving your reputation with lenders and vendors, business credit cards:
- Support efficient cash flow management through short-term financing and flexible payments
- Provide a clear separation of business and personal expenses for cleaner bookkeeping
- Opportunity to build a distinct business credit identity separate from your personal credit profile
When choosing a business credit card, be sure to check whether it reports positive payment activity to business credit bureaus—and whether it requires a personal guarantee that ties the debt to your personal finances. Selecting the right card helps your business grow responsibly and strengthen financial credibility.
How business credit card issuers report to credit bureaus
Most business credit card companies report all of your account and payment activity—like on-time or late payments—to at least one or more of the main credit bureaus.
The reported information typically includes:
- Business details such as company name, ownership, and subsidiaries
- Account-specific credit history, such as how long the account has been open
- Your credit card balance and outstanding debts
- Whether you're near, at, or above your credit limit
- Your number of recent credit applications
- The types of credit accounts you use
- Whether your debts have been referred to a collection agency
- Any records of insolvency or bankruptcy
Credit cards typically update your report at the end of each billing cycle, which can vary between about 28 to 31 days. If your credit report and credit card balance don't match, it's usually not a problem—just check back after it updates to find the latest information.
Note that unlike personal credit reports, your business credit report is publicly available. That doesn't mean just anyone can look at it, though. Usually it's entities like creditors and lenders, government agencies, or insurance companies that will pay to view your business credit report.
How Dun & Bradstreet determines your business credit score
D&B uses several scoring models, but the one you can most directly influence with a credit card is the PAYDEX score. It's a dollar-weighted measure of your past payment performance that runs on a 1 to 100 scale, built from the payment experiences that vendors and suppliers report to your file.
D&B groups PAYDEX scores into three risk bands:
| PAYDEX score | What it signals |
|---|---|
| 0–49 | High risk of late payment |
| 50–79 | Moderate risk |
| 80–100 | Low risk |
Most lenders treat a PAYDEX of 80 or higher as low risk, and D&B notes that repaying your debts on time or ahead of schedule is what moves the score up. Beyond PAYDEX, D&B also calculates the Delinquency Predictor Score, which estimates the odds of a business falling seriously behind, and the Failure Score (formerly the Financial Stress Score), which gauges the risk of a business shutting down. These scores draw on data from vendors, suppliers, financial institutions, and public records, alongside the D&B Rating that assesses overall financial health.
Keep in mind that D&B can only generate a PAYDEX score once enough vendors report your payment experiences, so opening a reporting card early gives your profile time to build.
What a D-U-N-S number is
A D-U-N-S (Data Universal Numbering System) number is a unique nine-digit identifier for businesses issued by Dun & Bradstreet (D&B). It functions similar to a Social Security number for your business. You (and other parties) can use that number to look up your business through D&B.
It typically takes about a month to receive a D-U-N-S number after you apply for it, but you can pay to speed up the process.
Can you get a business credit card with a D-U-N-S number?
Although your D-U-N-S number is linked to your business credit profile, it can't be used to apply for business credit cards.
Best practices to strengthen your D&B business credit profile
As a business owner, you can take important steps to ensure your account is set up for accurate reporting and strong credit building. Here's what to focus on:
- Update your business details: Make sure your profile is complete and your company information (like legal name, address, and ownership) is current
- Work with financial products that report to D&B: Not all lenders, credit card issuers, or vendors report payment activity to D&B. Choose business credit cards and accounts known to share data with the bureau so your positive activity is captured.
- Make payments on time: Timely payments and smart use of your credit lines are two of the biggest factors influencing your D&B PAYDEX score. Pay bills by their due dates, avoid maxing out credit limits, and maintain healthy financial practices.
- Pay early, not just on time: Paying ahead of the due date, rather than just by it, is what pushes a PAYDEX score from a solid 80 toward the 90 to 100 range that signals top-tier reliability
- Monitor your D&B credit file regularly: Check your D&B credit profile to ensure your accounts and payment history are accurately reflected. If you spot errors, work with D&B to request corrections or updates.
- Build credit across multiple channels: While credit cards are valuable, they're not the only way to build business credit. Vendor trade accounts, supplier relationships, and equipment leases also contribute important data to D&B and help create a more robust credit file.
Upholding these best practices can help you position your business for stronger credit scores, better financing opportunities, and improved trust with vendors, lenders, and partners.
How to check if your business credit card is reporting to D&B
Confirming that a new card is actually reaching your D&B file takes a few steps:
- Wait two billing cycles (about 60 days) before pulling your report so the issuer has time to submit the data and D&B has time to process it
- Pull your D&B file. CreditSignal, D&B's free monitoring tool, confirms whether a tradeline has posted, while the paid D&B portal shows full tradeline detail
- Look for the tradeline. Check the creditor name, highest limit, and payment-status notation, which is the field D&B uses to calculate your PAYDEX score
- Troubleshoot if it's missing. Confirm the issuer has your exact D-U-N-S number on file (this is why business credit cards with a D-U-N-S number on record report cleanly), then open a D&B support ticket with a recent statement
Vendors that report to Dun & Bradstreet
While opening a business credit card and paying it off regularly is one of the best ways to build business credit, it's not the only option—some vendors also report to Dun & Bradstreet.
By opening accounts with vendors that offer tradelines (credit accounts, often with Net 30 or similar short-term payment terms), your business can build credit by making on-time payments that get reported to D&B.
Using multiple types of credit, such as a combination of business credit cards and vendor accounts, helps diversify your credit profile and demonstrate your business's ability to manage various financial relationships.
Examples of vendors that commonly report to D&B include office supply companies, marketing services, and corporate merchandise providers such as:
- Quill
- Creative Analytics
- Shirtsy
While you can explore specific companies, the key is to look for vendors that clearly report to D&B or other major business credit bureaus, offer flexible payment terms, and match your business's actual operational needs—so you're building credit through meaningful, useful transactions.
How Marqeta optimized its card program for stronger credit management
Accurate, trackable card data is what keeps your on-time payments—and therefore your D&B tradeline—clean. Building a strong business credit history requires more than just obtaining a business credit card. It also demands an efficient, trackable card program and timely reconciliation. This was the challenge Marqeta, a global modern card issuing platform, faced with its legacy provider.
"Our previous corporate credit card program was very manual," says Megan Gemoll, Director of Corporate Accounting at Marqeta. "Every month we were doing a manual journal entry to upload all of our credit card transactions. There was no way for us to track who had and hadn't submitted receipts."
By switching from a legacy corporate card to Ramp's platform, Marqeta automated its card management and integrated seamlessly with Sage Intacct. "Instead of spending hours getting all of the corporate card transactions in manually, they now automatically sync over," Megan explains. "We're able to review our expenses much faster in the close process and analyze them."
With Ramp, Marqeta achieved timely reconciliation, faster month-end closes, and more accurate financial reporting. These improvements saved the finance team hours each month and positioned Marqeta to better manage spending, payments, and financial operations—all key factors in supporting stronger business credit management over time. Teams evaluating their options can also compare expense management platforms like Expensify, Navan, and Ramp to find the right fit for their workflows.
Build credit with a Ramp Business Credit Card
In addition to offering a best-in-class corporate business credit card and reporting payments to D&B, Ramp offers tools that allow you to take control of your business finances and build business credit.
Ramp's spend management platform gives you insight into your company's spending and suggests ways that you can cut costs to make your company more efficient. That makes Ramp different from other credit companies, which encourage more spending to earn points.
Take charge of your business finances, optimize your spending, and lay the groundwork for stronger credit and bigger opportunities ahead.
Take charge with Ramp.

FAQs
American Express business cards generally report to Dun & Bradstreet only if an account becomes seriously delinquent, so they don't actively build a positive PAYDEX score.
Yes, but Bank of America routes its business card data through the Small Business Financial Exchange (SBFE) rather than reporting directly to D&B.
The FNBO Business Edition Secured Mastercard reports to Dun & Bradstreet, Experian, and Equifax, and the Valley Visa Secured Business Card reports to the major business credit bureaus.
Lenders, vendors, and card issuers pull D&B data. Major issuers that report include Ramp, Capital One, Bank of America, U.S. Bank, Corpay One, and FNBO.


“Invoices, cards, tokens. The categories change but the principle doesn't: know where the money is going, remove the work around it, and make sure the spend is worth it.”
Maciej Mylik. Finance
ElevenLabs

“There's just no surprises anymore. No more waiting two months to find out how a job did. We know how it's doing as it's happening.”
Erich Kuss
Financial Systems Manager, Infinity Home Services

“More token spend isn’t proof that AI is working. Less isn’t proof that it isn’t. What matters is whether we’re buying the right level of intelligence for the work. Ramp lets us make that judgment in the same place we manage every other type of spend.”
Cody Nutt
Senior Director of Business Systems, Daxko

“Most banks treat the back office as a cost to keep down. We treat ours as a return to compound, which is why we run it on Ramp. Now we put our clients on Ramp, too.”
Patrick Gaughen
President & COO, Hingham Institution for Savings

“Browserbase builds infrastructure so AI agents can do real work. Ramp is doing the same for finance. It’s not another tool. It’s a system purpose-built for AI-driven finance, and that’s why we chose Ramp as our financial operating system from day one.”
Paul Klein IV
Founder & CEO, Browserbase

“We used to pay up to $20k a year for our AP platform. With Ramp, we’re earning back well over that amount. That's money that belongs to the mission now, not to the back-office software.”
Heidi Coffer
Chief Financial Officer, Boys & Girls Clubs of San Francisco

“The tricky thing about corporate travel policy is timing. We didn't need a stricter policy. We needed the policy to show up earlier. With Ramp Travel, it finally does.”
Keith Frantz
Director of Enterprise Risk Management, Prosper

“We're accountable to our funders, our partners, and the families we serve. That accountability starts with how we manage every dollar. Ramp makes it easy for our team to spend wisely, track in real time, and keep overhead low so more resources reach the families navigating infertility.”
Rachel Fruchtman
CFO, Jewish Fertility Foundation
